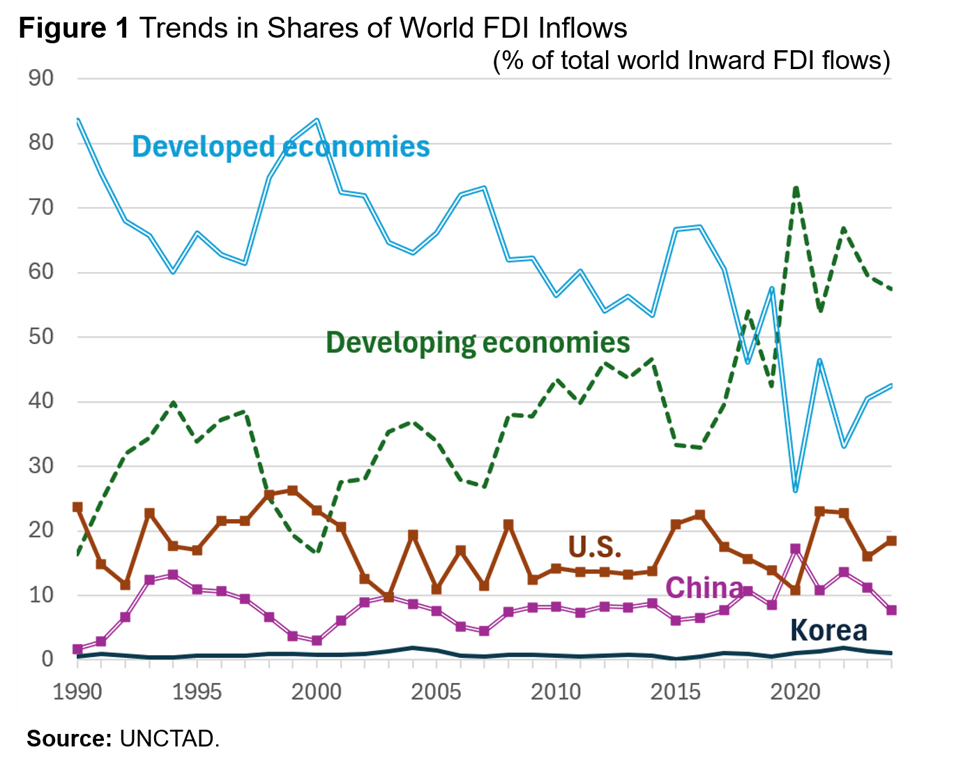
As shown in Figure 1, Foreign direct investment (FDI) inflows to developed economies accounted for nearly 84% of total world FDI inflows in 1990. Since then, their share has steadily declined, reaching 42.5% in 2024.
In contrast, although FDI inflows to developing economies have fluctuated over time, their overall share has shown an upward trend. Rising from 16.4% in 1990, the share increased to 57.5% in 2024, surpassing that of developed economies.
Korea's share of global FDI inflows remains relatively small compared with major economies such as the United States and China. Over the period 1990–2024, the United States accounted for an average of 17.5% of total world FDI inflows, while China accounted for 8.2%. By comparison, Korea's share averaged only 0.85%.
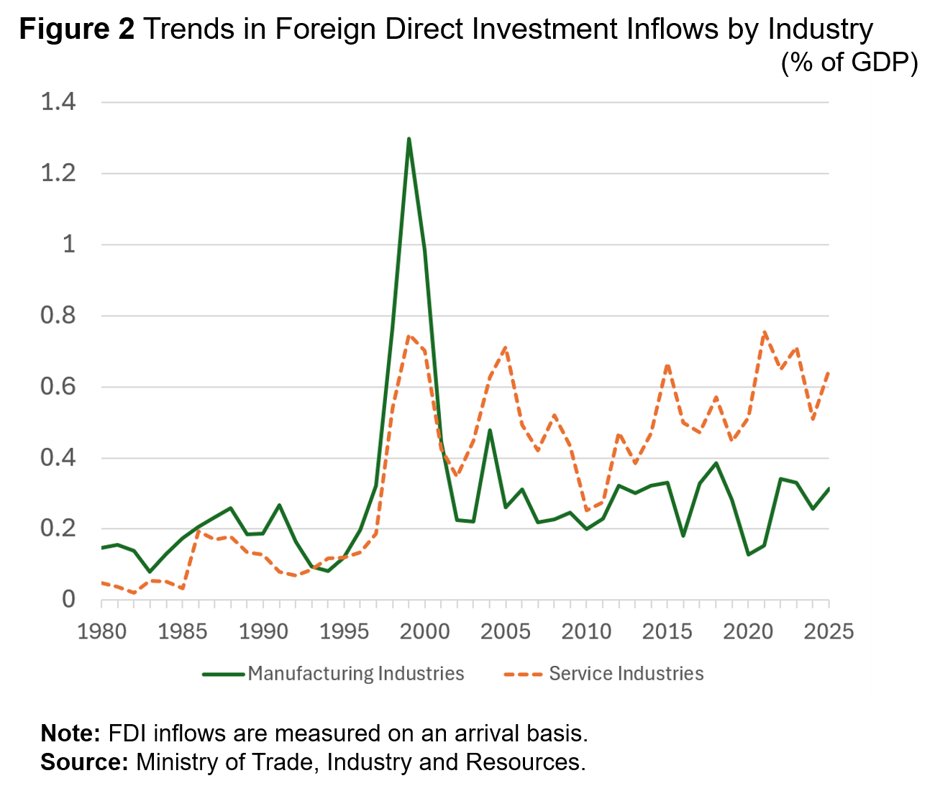
Figure 2 illustrates the trend in foreign direct investment (FDI) inflows into Korea over the period 1980–2025. Two notable patterns emerge.
First, FDI inflows increased sharply in 1999, immediately following the Asian financial crisis. This suggests that the post-crisis restructuring and asset sales of domestic firms may have contributed to the increase in FDI inflows.
Second, since the early 2000s, FDI has increasingly been directed toward the service sector rather than the manufacturing sector. Specifically, beginning in 2002, FDI inflows into the service sector exceeded those into the manufacturing sector, and this gap has persisted through 2025.
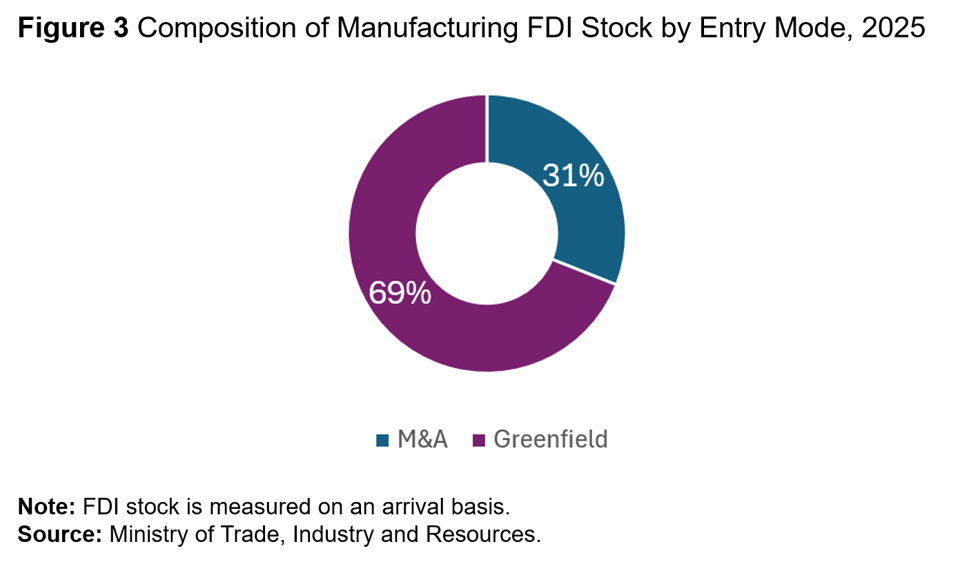
Within manufacturing, Figure 3 indicates that greenfield investment remains the dominant mode of entry. As of the end of 2025, approximately 69% of Korea's manufacturing FDI stock consisted of greenfield investment, while the remaining 31% consisted of M&A.

As shown in Figure 1, Foreign direct investment (FDI) inflows to developed economies accounted for nearly 84% of total world FDI inflows in 1990. Since then, their share has steadily declined, reaching 42.5% in 2024.
In contrast, although FDI inflows to developing economies have fluctuated over time, their overall share has shown an upward trend. Rising from 16.4% in 1990, the share increased to 57.5% in 2024, surpassing that of developed economies.
Korea's share of global FDI inflows remains relatively small compared with major economies such as the United States and China. Over the period 1990–2024, the United States accounted for an average of 17.5% of total world FDI inflows, while China accounted for 8.2%. By comparison, Korea's share averaged only 0.85%.
Figure 2 illustrates the trend in foreign direct investment (FDI) inflows into Korea over the period 1980–2025. Two notable patterns emerge.
First, FDI inflows increased sharply in 1999, immediately following the Asian financial crisis. This suggests that the post-crisis restructuring and asset sales of domestic firms may have contributed to the increase in FDI inflows.
Second, since the early 2000s, FDI has increasingly been directed toward the service sector rather than the manufacturing sector. Specifically, beginning in 2002, FDI inflows into the service sector exceeded those into the manufacturing sector, and this gap has persisted through 2025.
Within manufacturing, Figure 3 indicates that greenfield investment remains the dominant mode of entry. As of the end of 2025, approximately 69% of Korea's manufacturing FDI stock consisted of greenfield investment, while the remaining 31% consisted of M&A.