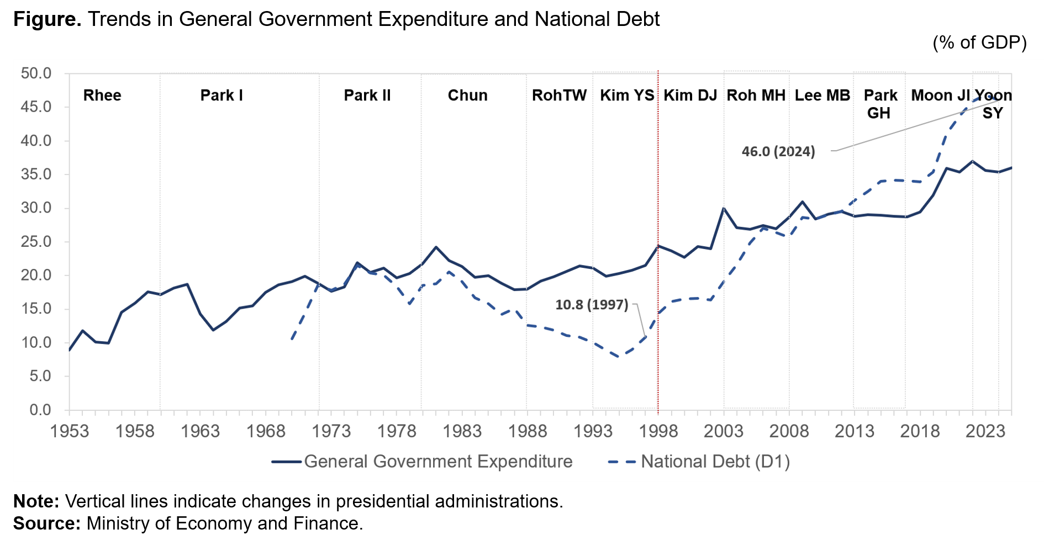
The figure illustrates the evolution of government expenditure and national debt as a share of GDP. During Korea’s high-growth period in the 1960s and 1970s, the size of government increased steadily alongside rapid economic development. However, under the Chun Doo-hwan administration in the 1980s, the share of government expenditure temporarily declined, reflecting the government's commitment to fiscal restraint and macroeconomic stabilization. Beginning with the Roh Tae-woo administration, government spending resumed its upward trend, with economic growth and fiscal expansion proceeding in parallel.
One particularly noteworthy feature is the trajectory of public debt. Prior to the Asian Financial Crisis, the debt-to-GDP ratio fluctuated in response to changing fiscal conditions but remained below 20 percent of GDP for most years. During the 1980s, fiscal tightening under the Chun administration reduced the debt ratio to nearly 10 percent of GDP. In a rapidly growing economy, changes of this magnitude may not appear remarkable in themselves. Nevertheless, the ability to resist the temptation of debt-financed spending in a developing-country environment—where demands for public expenditure are often substantial—carries important policy implications.
This conservative fiscal approach may have limited the government's ability to use fiscal policy as an active stabilization tool. However, it also helped Korea avoid the cycle of chronic fiscal deficits and monetary expansion that contributed to recurrent macroeconomic instability in many developing economies.
The post-crisis period presents a markedly different picture. Since the Asian Financial Crisis, the government debt ratio has risen steadily. Debt stood at around 10 percent of GDP immediately before the crisis, but over the following two decades it increased more than fourfold, exceeding 40 percent of GDP and reaching 46 percent by 2024. Part of this increase reflects fiscal stimulus measures implemented during and after the crisis, as well as the conversion of restructuring-related public liabilities into government debt. Even so, Korea’s debt ratio remains lower than that of most advanced Western economies. Nevertheless, the long-term upward trend represents a significant departure from the fiscal pattern that characterized much of Korea’s earlier development period.

The figure illustrates the evolution of government expenditure and national debt as a share of GDP. During Korea’s high-growth period in the 1960s and 1970s, the size of government increased steadily alongside rapid economic development. However, under the Chun Doo-hwan administration in the 1980s, the share of government expenditure temporarily declined, reflecting the government's commitment to fiscal restraint and macroeconomic stabilization. Beginning with the Roh Tae-woo administration, government spending resumed its upward trend, with economic growth and fiscal expansion proceeding in parallel.
One particularly noteworthy feature is the trajectory of public debt. Prior to the Asian Financial Crisis, the debt-to-GDP ratio fluctuated in response to changing fiscal conditions but remained below 20 percent of GDP for most years. During the 1980s, fiscal tightening under the Chun administration reduced the debt ratio to nearly 10 percent of GDP. In a rapidly growing economy, changes of this magnitude may not appear remarkable in themselves. Nevertheless, the ability to resist the temptation of debt-financed spending in a developing-country environment—where demands for public expenditure are often substantial—carries important policy implications.
This conservative fiscal approach may have limited the government's ability to use fiscal policy as an active stabilization tool. However, it also helped Korea avoid the cycle of chronic fiscal deficits and monetary expansion that contributed to recurrent macroeconomic instability in many developing economies.
The post-crisis period presents a markedly different picture. Since the Asian Financial Crisis, the government debt ratio has risen steadily. Debt stood at around 10 percent of GDP immediately before the crisis, but over the following two decades it increased more than fourfold, exceeding 40 percent of GDP and reaching 46 percent by 2024. Part of this increase reflects fiscal stimulus measures implemented during and after the crisis, as well as the conversion of restructuring-related public liabilities into government debt. Even so, Korea’s debt ratio remains lower than that of most advanced Western economies. Nevertheless, the long-term upward trend represents a significant departure from the fiscal pattern that characterized much of Korea’s earlier development period.