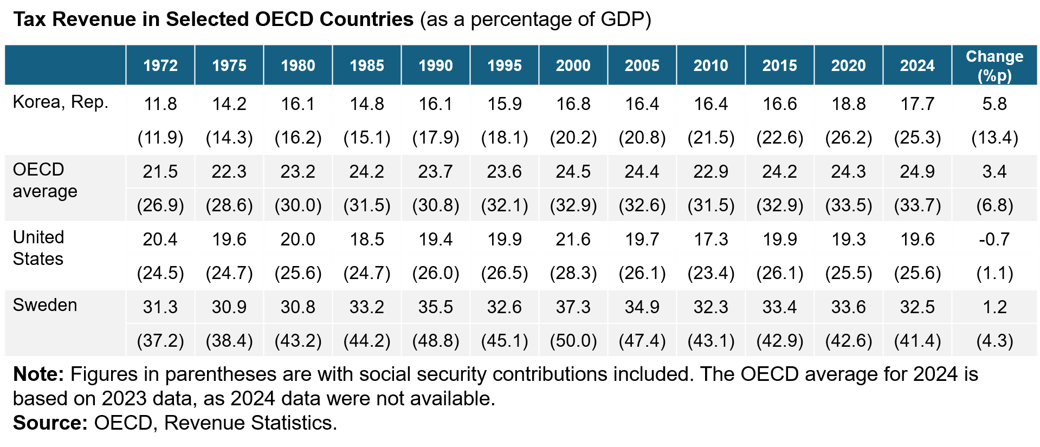
Korea’s tax burden has increased steadily alongside economic growth. The table below compares changes in tax burdens over the past several decades across Korea, the OECD average, and selected advanced economies. It shows that Korea’s tax burden has risen much more rapidly than those of most other advanced countries during this period. By contrast, mature economies such as the United States and Sweden have experienced relatively little change in their tax burden levels.
Until 1995, just before the Asian Financial Crisis, social security contributions in Korea remained relatively modest. As a result, the tax burden and the broader national burden—including social security contributions—were at similar levels. Since the crisis, however, the expansion of social insurance programs has contributed to a substantial increase in the overall burden.
As of 2024, Korea’s effective tax burden, including social security contributions, stood at 25.3% of GDP. Although this remains 8.4 percentage points below the OECD average, the gap is likely to narrow as population aging and expanding welfare expenditures place increasing demands on public finances.
At the same time, there is no single “optimal” level of taxation. The level and structure of taxation in each country reflect its unique institutions, economic conditions, and policy choices. Consequently, neither economic theory nor the experiences of other countries can reliably predict the future path of Korea’s tax system. As the table illustrates, even among advanced economies there is considerable variation: the United States maintains a tax burden broadly comparable to Korea’s, while Sweden’s effective tax burden approaches one-half of national income.

Korea’s tax burden has increased steadily alongside economic growth. The table below compares changes in tax burdens over the past several decades across Korea, the OECD average, and selected advanced economies. It shows that Korea’s tax burden has risen much more rapidly than those of most other advanced countries during this period. By contrast, mature economies such as the United States and Sweden have experienced relatively little change in their tax burden levels.
Until 1995, just before the Asian Financial Crisis, social security contributions in Korea remained relatively modest. As a result, the tax burden and the broader national burden—including social security contributions—were at similar levels. Since the crisis, however, the expansion of social insurance programs has contributed to a substantial increase in the overall burden.
As of 2024, Korea’s effective tax burden, including social security contributions, stood at 25.3% of GDP. Although this remains 8.4 percentage points below the OECD average, the gap is likely to narrow as population aging and expanding welfare expenditures place increasing demands on public finances.
At the same time, there is no single “optimal” level of taxation. The level and structure of taxation in each country reflect its unique institutions, economic conditions, and policy choices. Consequently, neither economic theory nor the experiences of other countries can reliably predict the future path of Korea’s tax system. As the table illustrates, even among advanced economies there is considerable variation: the United States maintains a tax burden broadly comparable to Korea’s, while Sweden’s effective tax burden approaches one-half of national income.