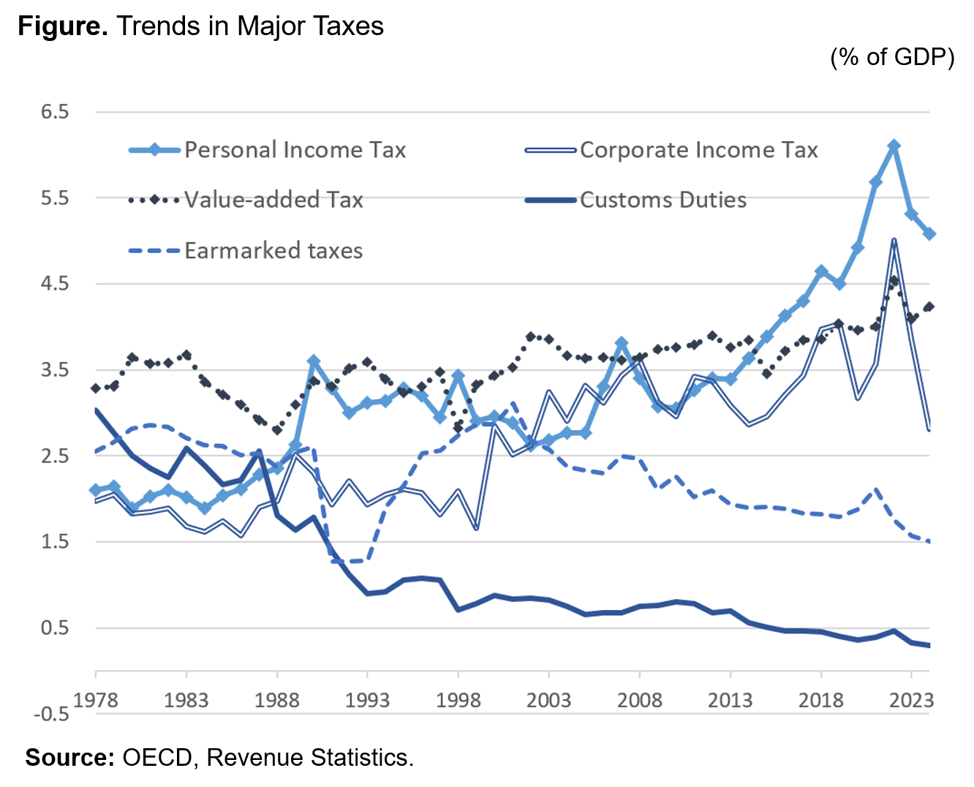
The figure above illustrates the long-term trends in major sources of tax revenue in Korea. Since its introduction in 1977, the value-added tax (VAT) has remained one of the country's most important sources of revenue. VAT revenues increased steadily from 3.3 percent of GDP in 1978 to 4.2 percent in 2024.
Personal and corporate income taxes, which together constitute income taxation, have also increased steadily over time. Following the Asian Financial Crisis, however, the share of personal income tax declined somewhat, and the shares of personal and corporate income taxes remained at similar levels for an extended period. Since 2008, the share of personal income tax has risen rapidly and has consistently exceeded that of corporate income tax.
Customs duties were a more important source of revenue than either personal or corporate income taxes until the 1980s, but their importance declined rapidly with the expansion of free trade and economic liberalization in the 1990s. In developing countries, where information on taxpayers is often limited, the share of personal income taxation tends to be relatively low, while trade-related taxes—which are easier to collect because the tax base passes through ports and airports—typically account for a larger share of total revenue.
One notable feature of Korea's tax system is the persistent importance of earmarked taxes. With the exception of a temporary decline in the early 1990s, earmarked taxes have remained an important source of revenue throughout the entire period under consideration. Over the past four decades, revenues from earmarked taxes have remained at roughly 2 percent of GDP. Prior to the Asian Financial Crisis, earmarked taxes generated more revenue than either personal or corporate income taxes, and even today they continue to provide revenues comparable to those generated by the two major income taxes.
During the 1980s, the Defense Tax was a particularly important source of revenue, generating tax receipts equivalent to around 2 percent of GDP. Following its abolition in 1991, earmarked tax revenues declined substantially. In response, the government introduced the Transportation Tax and the Special Tax for Rural Development in 1994, allowing earmarked tax revenues to recover to roughly their levels of the 1980s.

The figure above illustrates the long-term trends in major sources of tax revenue in Korea. Since its introduction in 1977, the value-added tax (VAT) has remained one of the country's most important sources of revenue. VAT revenues increased steadily from 3.3 percent of GDP in 1978 to 4.2 percent in 2024.
Personal and corporate income taxes, which together constitute income taxation, have also increased steadily over time. Following the Asian Financial Crisis, however, the share of personal income tax declined somewhat, and the shares of personal and corporate income taxes remained at similar levels for an extended period. Since 2008, the share of personal income tax has risen rapidly and has consistently exceeded that of corporate income tax.
Customs duties were a more important source of revenue than either personal or corporate income taxes until the 1980s, but their importance declined rapidly with the expansion of free trade and economic liberalization in the 1990s. In developing countries, where information on taxpayers is often limited, the share of personal income taxation tends to be relatively low, while trade-related taxes—which are easier to collect because the tax base passes through ports and airports—typically account for a larger share of total revenue.
One notable feature of Korea's tax system is the persistent importance of earmarked taxes. With the exception of a temporary decline in the early 1990s, earmarked taxes have remained an important source of revenue throughout the entire period under consideration. Over the past four decades, revenues from earmarked taxes have remained at roughly 2 percent of GDP. Prior to the Asian Financial Crisis, earmarked taxes generated more revenue than either personal or corporate income taxes, and even today they continue to provide revenues comparable to those generated by the two major income taxes.
During the 1980s, the Defense Tax was a particularly important source of revenue, generating tax receipts equivalent to around 2 percent of GDP. Following its abolition in 1991, earmarked tax revenues declined substantially. In response, the government introduced the Transportation Tax and the Special Tax for Rural Development in 1994, allowing earmarked tax revenues to recover to roughly their levels of the 1980s.