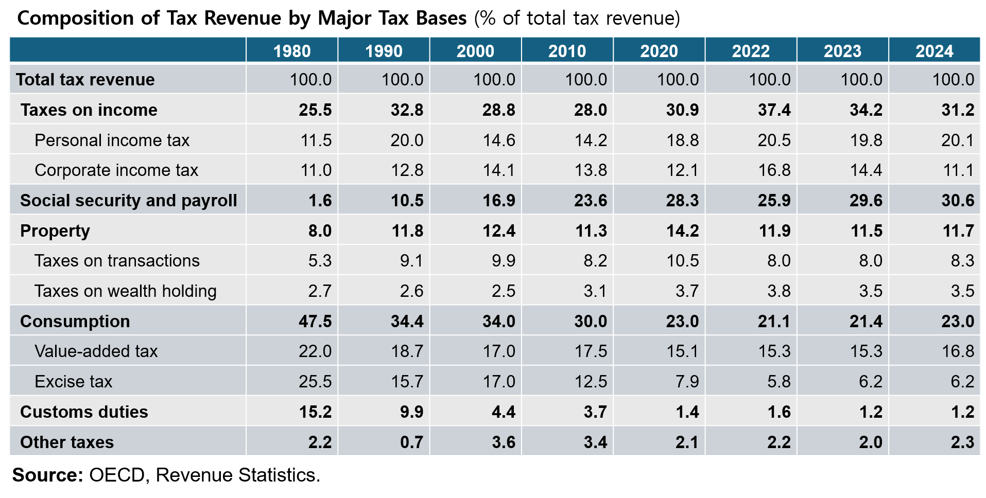
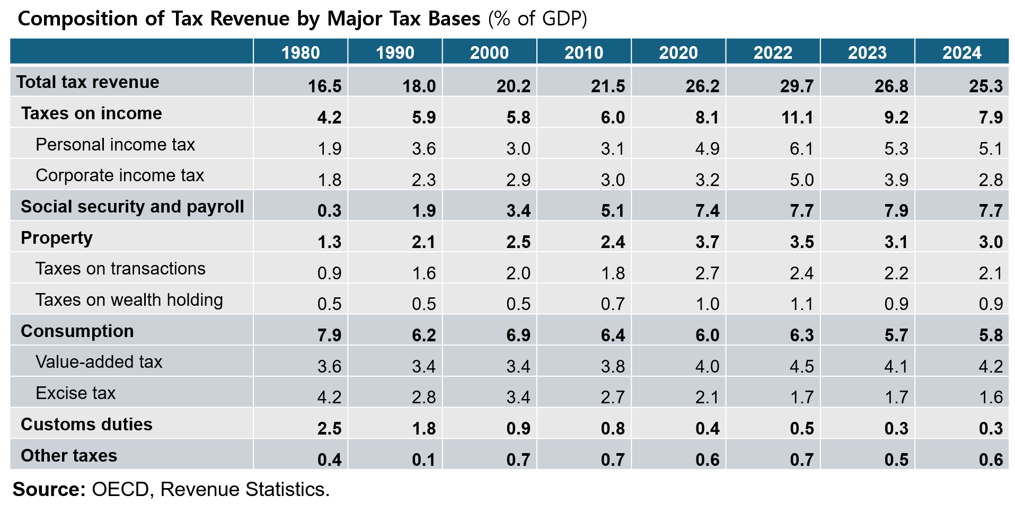
The table above shows changes in the composition of tax revenues by major tax bases, indicating that Korea's tax structure has undergone substantial transformation over the past four decades. Broadly defined income taxation—including personal income taxes, corporate income taxes, and social security contributions—accounted for only 26.1 percent of total tax revenue in 1980, but its share had risen to 61.8 percent by 2024.
The share of property taxation also increased over the same period, although its evolution was less consistent than that of income taxation. While the share of these direct taxes, which tend to face relatively strong taxpayer resistance, has steadily increased, the share of consumption taxes declined sharply from 47.5 percent of total tax revenue to 23.0 percent. This shift suggests that Korea's tax structure has moved, at least to some extent, toward the pattern observed in advanced economies. Customs duties, which accounted for a substantial 15.2 percent of total tax revenue in 1980, fell dramatically to 2.3 percent by 2024, reflecting the country's increasing economic openness and the expansion of free trade.
Judging solely from these broad trends in the tax base, one might conclude that Korea's tax structure has gradually evolved toward an advanced-economy model, characterized by a larger role for direct income taxation and a diminished reliance on indirect consumption taxation. The rapid increase in social security contributions in recent years, which reflects one aspect of the expansion of government-provided social welfare, is another notable development. However, a closer examination of the internal composition of the tax system reveals that Korea still retains many features commonly associated with developing-country tax structures.
First, the share of corporate income taxation remains relatively high compared with that in advanced economies. Because corporate taxation, which falls primarily on capital income, generally creates larger economic distortions than labor income taxation, optimal tax theory predicts that its relative importance should be limited. Indeed, in most advanced economies, the share of personal income taxation substantially exceeds that of corporate income taxation.
Second, the relatively large role played by various excise taxes, in addition to the value-added tax (VAT), is also difficult to justify from an efficiency perspective. In theory, a broad-based consumption tax is economically equivalent to a flat-rate tax on labor income and therefore tends to generate relatively small distortions. In Korea, however, the VAT base is not particularly broad because numerous exemptions and preferential treatments have been introduced, partly to protect small self-employed businesses. Moreover, a considerable portion of excise taxation takes the form of earmarked taxes, which may constitute an additional source of economic inefficiency because of the distortions associated with both commodity-specific taxation and revenue earmarking.
Finally, within property taxation, transaction taxes—which generally face lower taxpayer resistance—account for a much larger share of revenue than recurrent taxes on property holdings.

The table above shows changes in the composition of tax revenues by major tax bases, indicating that Korea's tax structure has undergone substantial transformation over the past four decades. Broadly defined income taxation—including personal income taxes, corporate income taxes, and social security contributions—accounted for only 26.1 percent of total tax revenue in 1980, but its share had risen to 61.8 percent by 2024.
The share of property taxation also increased over the same period, although its evolution was less consistent than that of income taxation. While the share of these direct taxes, which tend to face relatively strong taxpayer resistance, has steadily increased, the share of consumption taxes declined sharply from 47.5 percent of total tax revenue to 23.0 percent. This shift suggests that Korea's tax structure has moved, at least to some extent, toward the pattern observed in advanced economies. Customs duties, which accounted for a substantial 15.2 percent of total tax revenue in 1980, fell dramatically to 2.3 percent by 2024, reflecting the country's increasing economic openness and the expansion of free trade.
Judging solely from these broad trends in the tax base, one might conclude that Korea's tax structure has gradually evolved toward an advanced-economy model, characterized by a larger role for direct income taxation and a diminished reliance on indirect consumption taxation. The rapid increase in social security contributions in recent years, which reflects one aspect of the expansion of government-provided social welfare, is another notable development. However, a closer examination of the internal composition of the tax system reveals that Korea still retains many features commonly associated with developing-country tax structures.
First, the share of corporate income taxation remains relatively high compared with that in advanced economies. Because corporate taxation, which falls primarily on capital income, generally creates larger economic distortions than labor income taxation, optimal tax theory predicts that its relative importance should be limited. Indeed, in most advanced economies, the share of personal income taxation substantially exceeds that of corporate income taxation.
Second, the relatively large role played by various excise taxes, in addition to the value-added tax (VAT), is also difficult to justify from an efficiency perspective. In theory, a broad-based consumption tax is economically equivalent to a flat-rate tax on labor income and therefore tends to generate relatively small distortions. In Korea, however, the VAT base is not particularly broad because numerous exemptions and preferential treatments have been introduced, partly to protect small self-employed businesses. Moreover, a considerable portion of excise taxation takes the form of earmarked taxes, which may constitute an additional source of economic inefficiency because of the distortions associated with both commodity-specific taxation and revenue earmarking.
Finally, within property taxation, transaction taxes—which generally face lower taxpayer resistance—account for a much larger share of revenue than recurrent taxes on property holdings.